Tax and Compliance for FSPs: South Africa Guide 2026
Managing tax and compliance obligations remains one of the most critical yet challenging responsibilities for financial services providers operating in South Africa. Independent financial brokers, advisors, and FSPs must navigate an increasingly complex regulatory landscape that demands technical expertise, systematic processes, and constant vigilance. The intersection of taxation requirements and compliance monitoring creates a framework where missteps can result in substantial penalties, reputational damage, and potential license suspension.
Understanding the Tax and Compliance Landscape in South African Financial Services
The South African regulatory environment for financial services providers has undergone significant transformation in recent years. The introduction of the Conduct of Financial Institutions Act (COFI) alongside existing frameworks such as the Financial Advisory and Intermediary Services Act (FAIS) has created a multi-layered compliance structure.
Key regulatory bodies and their tax and compliance mandates include:
- Financial Sector Conduct Authority (FSCA) – oversees conduct, market integrity, and consumer protection
- South African Revenue Service (SARS) – administers tax law and ensures compliance with Income Tax Act provisions
- Financial Intelligence Centre (FIC) – enforces anti-money laundering and counter-terrorism financing measures
- Information Regulator – monitors compliance with Protection of Personal Information Act (POPIA)
These authorities work in concert, yet each maintains distinct reporting requirements, deadlines, and enforcement mechanisms. Financial services providers must therefore adopt a holistic approach that addresses tax obligations whilst simultaneously managing regulatory compliance across multiple dimensions.
Tax Obligations Specific to Financial Services Providers
FSPs face unique taxation challenges that extend beyond standard corporate tax requirements. Commission income, fee structures, and value-added tax (VAT) considerations create complexities that demand specialized knowledge.
Commission income received from product providers must be correctly classified and declared. Many independent brokers operate as sole proprietors or personal service companies, which affects their tax treatment significantly. The distinction between employees and independent contractors also carries tax implications that impact both the FSP and individual representatives.
| Tax Type | FSP Obligation | Filing Frequency | Key Consideration |
|---|---|---|---|
| Income Tax | Provisional tax on commission and fees | Twice yearly | Estimated taxable income calculations |
| VAT | Registration mandatory if turnover exceeds threshold | Monthly or bi-monthly | Input tax credits on business expenses |
| PAYE | Withholding for employed representatives | Monthly | Distinguish employees from contractors |
| Skills Development Levy | 1% of remuneration | Monthly | Payroll calculation requirements |
Understanding these obligations forms the foundation of effective tax and compliance management. The World Bank’s research on tax compliance innovations demonstrates that jurisdictions with clear frameworks and digital systems achieve substantially higher voluntary compliance rates.
FICA Compliance and Risk Management Control Programme Requirements
The Financial Intelligence Centre Act (FICA) imposes stringent obligations on FSPs regarding client identification, verification, and ongoing monitoring. These requirements directly intersect with tax and compliance frameworks, as proper FICA documentation supports accurate tax reporting and reduces exposure to regulatory sanctions.
Establishing Your Risk Management and Compliance Programme
Every FSP must maintain a documented Risk Management and Compliance Programme (RMCP) that addresses FICA obligations alongside broader compliance requirements. This programme serves as your operational blueprint for managing customer due diligence, record-keeping, and suspicious transaction reporting.
Core components of an effective RMCP include:
- Client acceptance policy with risk-based assessment criteria
- Customer identification and verification procedures
- Ongoing due diligence and monitoring protocols
- Record retention systems compliant with five-year minimum requirement
- Training programmes for representatives and support staff
- Internal controls and compliance testing mechanisms
The RMCP must be reviewed annually and updated whenever material changes occur in your business model, product offerings, or the regulatory environment. Many independent brokers find that establishing robust systems initially requires significant investment, yet the long-term benefits include reduced compliance costs, enhanced client trust, and protection against regulatory enforcement.
For FSPs requiring assistance with RMCP development, specialized compliance monitoring services can provide frameworks tailored to broker workflows whilst ensuring alignment with current regulatory expectations.
Practical Client Onboarding Checklist
Implementing systematic client onboarding processes ensures FICA compliance whilst creating documentation that supports tax reporting accuracy. Each new client engagement should follow a standardized protocol:
- Obtain certified copy of South African ID, passport, or company registration documents
- Verify residential address through utility bill, bank statement, or municipal account (not older than three months)
- Complete client questionnaire capturing occupation, income sources, and investment objectives
- Conduct risk assessment using documented criteria aligned with your RMCP
- Document source of funds and expected transaction patterns
- Obtain signed mandate authorizing you to act as financial services provider
- Record all information in secure, POPIA-compliant client management system
This documentation serves dual purposes: demonstrating FICA compliance during regulatory inspections and providing substantiation for tax reporting when commission income relates to specific client transactions.
POPIA Requirements for Financial Services Data Management
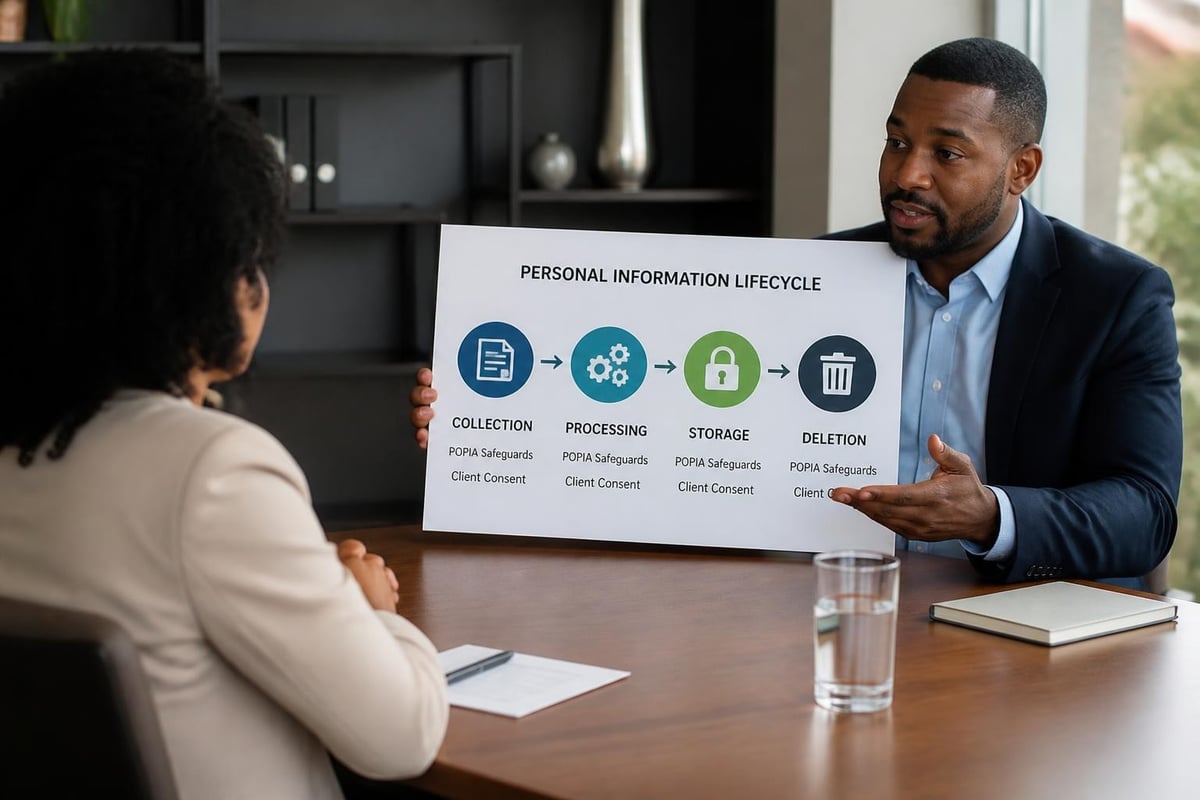
The Protection of Personal Information Act fundamentally changed how FSPs collect, process, store, and share client information. Tax and compliance obligations under POPIA extend beyond simple data protection to encompass accountability principles that require documented evidence of lawful processing.
Eight Conditions for Lawful Processing
POPIA establishes eight conditions that govern all processing of personal information. Financial services providers must ensure compliance with each condition throughout the client lifecycle:
| Condition | Practical Application for FSPs | Tax and Compliance Link |
|---|---|---|
| Accountability | Appoint Information Officer; maintain processing records | Demonstrates governance for regulatory inspections |
| Processing Limitation | Collect only necessary client data; obtain consent | Reduces data breach exposure and regulatory risk |
| Purpose Specification | Define purposes before collection; inform clients | Supports defensible tax documentation practices |
| Further Processing Limitation | Use data only for stated purposes | Prevents unauthorized sharing with SARS or others |
| Information Quality | Maintain accurate, complete, current records | Ensures tax reporting reflects actual client circumstances |
| Openness | Provide privacy notices; respond to access requests | Builds client trust and demonstrates transparency |
| Security Safeguards | Implement technical and organizational measures | Protects sensitive financial and tax-related information |
| Data Subject Participation | Honor rights to access, correction, deletion | Maintains data integrity for compliance purposes |
Financial services providers handle particularly sensitive personal information including financial circumstances, investment holdings, and tax reference numbers. The European Commission’s VAT invoicing guidance illustrates how jurisdictions worldwide are strengthening data protection requirements within tax administration frameworks.
Implementing POPIA-Compliant Systems
Achieving POPIA compliance requires both policy frameworks and practical implementation across your technology infrastructure, physical filing systems, and business processes.
Technology considerations:
- Client management software with encryption, access controls, and audit trails
- Secure email systems for transmitting sensitive client information
- Cloud storage solutions with data sovereignty guarantees (South African servers)
- Regular backups with tested disaster recovery protocols
- Multi-factor authentication for all systems containing personal information
Physical security measures:
- Locked filing cabinets for paper records containing client information
- Clean desk policy preventing unauthorized access to documents
- Secure disposal (shredding) of physical records containing personal information
- Visitor logs and restricted access to areas with client files
Independent brokers operating from home offices must implement equivalent security measures, recognizing that regulatory expectations apply regardless of practice size. The Information Regulator has demonstrated willingness to investigate complaints and impose penalties on FSPs of all sizes.
FAIS Compliance Framework for Independent Brokers
The Financial Advisory and Intermediary Services Act establishes licensing, conduct, and competency requirements for financial services providers. Tax and compliance obligations under FAIS intersect with taxation frameworks through fit and proper assessments, financial soundness requirements, and ongoing reporting obligations.
Fit and Proper Requirements
FAIS requires that key individuals and FSPs maintain fit and proper status, which includes financial soundness criteria directly relevant to tax compliance. The FSCA assesses:
- Submission of annual financial statements demonstrating positive net asset value
- Absence of tax debt or payment arrangements with SARS for outstanding liabilities
- Professional indemnity insurance maintaining minimum coverage levels
- Financial resources sufficient to meet operational obligations and potential liabilities
Tax non-compliance can trigger fit and proper concerns, potentially resulting in license conditions, suspension, or withdrawal. FSPs facing temporary tax challenges should proactively engage with the FSCA rather than attempting to conceal difficulties.
Representative Oversight and Compliance Monitoring
FSPs bear accountability for representatives acting under their license. This creates tax and compliance obligations extending beyond your own affairs to encompass supervision, training, and monitoring of individuals conducting business under your authority.
Essential representative management practices include:
- Pre-appointment competency verification through RE exam training and qualification checks
- Signed representative agreements defining responsibilities, commission structures, and compliance obligations
- Regular file reviews assessing advice quality, documentation standards, and regulatory adherence
- Ongoing training addressing product knowledge, regulatory updates, and compliance procedures
- Commission processing systems with built-in compliance checks
- Monitoring systems flagging potential breaches for investigation
The intersection of representative oversight and tax compliance manifests most clearly in commission structures. FSPs must accurately classify representatives (employees versus independent contractors), withhold appropriate taxes, and maintain documentation supporting these classifications during SARS or FSCA inspections.
Navigating COFI Implementation and Conduct Standards
The Conduct of Financial Institutions Act introduces heightened conduct standards that will eventually replace FAIS upon full implementation. While transition timelines remain subject to regulatory announcements, FSPs should begin aligning practices with COFI principles now.
Fair Treatment of Customers
COFI emphasizes fair customer treatment throughout the product lifecycle. This principles-based approach affects tax and compliance management by requiring FSPs to demonstrate that business decisions prioritize client interests.
Practical applications include:
- Fee and commission disclosures enabling clients to understand total costs
- Product comparisons showing alternatives and explaining recommendations
- Conflict of interest management preventing unsuitable advice motivated by commission
- Complaints handling systems addressing client concerns promptly and fairly
These requirements create documentation that supports tax reporting transparency whilst demonstrating regulatory compliance. The Brookings Institution’s research on behavioral compliance shows that transparency mechanisms significantly increase voluntary adherence to both tax and conduct standards.
Product Governance and Distribution
COFI introduces product governance requirements affecting how FSPs select, distribute, and monitor financial products. Tax and compliance considerations emerge through commission arrangements, product provider relationships, and documentation of distribution decisions.
FSPs must assess:
- Product provider financial strength and regulatory standing
- Commission structures and potential conflicts affecting advice impartiality
- Product features, costs, and target market alignment
- Ongoing product performance monitoring and review triggers
- Documentation supporting product selection for specific client circumstances
Product governance frameworks create audit trails demonstrating that commission income results from suitable product recommendations rather than conflicted advice. This documentation protects FSPs during regulatory examinations whilst supporting defensible tax positions regarding business income sources.
Practical Compliance Implementation for Independent Brokers
Translating regulatory requirements into daily operational practices represents the greatest challenge for independent brokers and small FSPs. Tax and compliance management demands systematic approaches rather than reactive responses to regulatory correspondence.
Building Your Annual Compliance Calendar
Effective tax and compliance management begins with comprehensive planning that anticipates deadlines, identifies resource requirements, and builds accountability into your business rhythm.
| Month | Tax Obligations | Compliance Activities | Documentation Due |
|---|---|---|---|
| January-February | Prepare annual financial statements | Review RMCP for annual updates | Submit previous year financials to FSCA |
| March | First provisional tax payment | Conduct internal file audits | Update training records |
| April-May | Personal tax returns for individuals | Review POPIA processing records | Renew professional indemnity insurance |
| June-July | Mid-year tax planning review | Representative competency assessments | Submit mid-year compliance reports |
| August | Second provisional tax payment | Client file documentation review | Update client risk assessments |
| September-October | VAT reconciliation and planning | Review product governance frameworks | Annual FICA risk assessment |
| November | Skills development levy verification | Year-end compliance self-assessment | Prepare for FSCA inspections |
| December | Final tax provisions and accruals | Staff training on regulatory updates | Archive completed client files |
This calendar should be customized based on your specific license category, business model, and representative structure. Visit Holistic Compliance Management Solutions for resources supporting compliance calendar implementation tailored to broker workflows.
Essential Technology Systems
Independent brokers frequently underestimate technology requirements for effective tax and compliance management. Modern regulatory expectations assume digital systems providing audit trails, version control, and secure access management.
Minimum technology infrastructure includes:
- Client relationship management (CRM) system with compliance features
- Document management solution with encryption and access controls
- Accounting software generating tax-compliant financial reports
- Email archiving ensuring retrievability during investigations
- Calendar and task management tools tracking compliance deadlines
- Secure client portal enabling document exchange without email attachments
Cloud-based solutions offer independent brokers enterprise-grade capabilities without capital expenditure, yet providers must verify data residency compliance with POPIA requirements. Many international platforms now offer South African hosting options addressing sovereignty concerns.
Tax Planning Strategies for Financial Services Providers
Strategic tax planning enables FSPs to minimize liabilities whilst maintaining full compliance with revenue laws. Understanding available deductions, timing opportunities, and structural options creates substantial financial advantages.
Deductible Business Expenses
FSPs can claim numerous expenses against commission and fee income, reducing taxable profits. Careful documentation and business purpose justification ensure deductions withstand SARS scrutiny.
Commonly claimed expenses include:
- Professional indemnity insurance premiums
- Regulatory examination fees and continuing professional development
- License fees, FSCA levies, and industry association memberships
- Client relationship expenses (within prescribed limits)
- Marketing, advertising, and business development costs
- Technology subscriptions, software licenses, and hardware
- Office rent, utilities, and home office portions (for qualifying home-based practices)
- Professional fees for accountants, compliance consultants, and legal advisors
- Travel expenses for client meetings and business development
Documentation requirements extend beyond simple receipts. SARS increasingly demands evidence of business purpose, particularly for expenses that might include personal benefit components. Maintain contemporaneous records explaining the business rationale for significant expenditures.
Retirement Funding and Tax Efficiency
Financial services providers should leverage retirement funding vehicles both for personal financial planning and tax optimization. Contributions to retirement annuities and pension funds offer immediate tax deductions whilst building long-term wealth.
For the 2026 tax year, individuals can deduct the lesser of R350,000 or 27.5% of taxable income for retirement contributions. Independent brokers with variable income should structure contributions to maximize deductions during high-income years whilst maintaining adequate cash flow.
Tax-free savings accounts complement retirement funding by creating investment growth without ongoing tax drag. The annual contribution limit of R36,000 (lifetime limit R500,000) enables systematic wealth accumulation particularly valuable for brokers building emergency reserves or saving for business expansion.
The U.S. Internal Revenue Service compliance resources demonstrate how transparent tax planning distinguished from aggressive tax avoidance creates sustainable approaches that withstand regulatory examination.
Managing Regulatory Inspections and Examinations
Both SARS and the FSCA conduct inspections, audits, and examinations of financial services providers. Preparation, professional conduct, and comprehensive documentation separate routine inspections from protracted investigations.
FSCA On-Site Visits
The Financial Sector Conduct Authority conducts both scheduled and unannounced inspections assessing compliance with FAIS, FICA, and emerging COFI requirements. Tax and compliance documentation intersects during these examinations as inspectors verify financial soundness, representative oversight, and client file quality.
Preparation strategies include:
- Maintain inspection-ready files with standardized documentation
- Conduct quarterly internal audits identifying gaps before regulators arrive
- Create inspection response teams designating who handles document requests
- Prepare summary presentations explaining your compliance framework
- Review recent FSCA enforcement actions understanding current focus areas
During inspections, provide requested documentation promptly whilst avoiding volunteering unnecessary information. Answer questions directly and honestly, seeking clarification when requests seem unclear. Inspectors appreciate organized, cooperative FSPs who demonstrate genuine commitment to compliance.
SARS Tax Audits
Revenue Service audits examine whether tax returns accurately reflect business income, expenses, and tax calculations. Financial services providers face particular scrutiny regarding commission income recognition, expense deductibility, and VAT calculations.
Common SARS audit triggers include:
- Significant year-over-year income fluctuations without explanation
- Expense ratios substantially exceeding industry norms
- Home office deductions appearing excessive relative to business scale
- VAT input claims disproportionate to business activities
- Discrepancies between third-party data (product provider commission statements) and tax returns
When SARS initiates an audit, engage professional tax advisors immediately. The technical complexity of tax law combined with the stakes involved justify expert representation. Respond to information requests within specified timeframes, maintaining professional communication throughout the process.
The Tax Foundation’s analysis of compliance gaps illustrates how systematic record-keeping and transparent reporting substantially reduce audit risk whilst accelerating resolution when examinations occur.
Building a Culture of Compliance Within Your Practice
Sustainable tax and compliance management requires embedding these obligations into your practice culture rather than treating them as administrative burdens. Independent brokers who embrace compliance as competitive advantage rather than cost center build more valuable, resilient businesses.
Training and Development
Regular training ensures that you and your representatives understand current requirements, recognize compliance risks, and implement best practices consistently. Training frequency should reflect regulatory change pace, typically quarterly sessions supplemented by immediate updates when significant changes occur.
Effective training programmes cover:
- Regulatory updates affecting daily client interactions
- Case studies illustrating common compliance failures and consequences
- Practical workshops on documentation, file management, and record-keeping
- Product-specific training addressing features, risks, and target markets
- Ethics scenarios building judgment around conflicts and customer treatment
Document all training through attendance registers, content materials, and competency assessments. This documentation demonstrates compliance commitment during regulatory inspections whilst supporting representative development.
Internal Controls and Monitoring
Systematic monitoring detects compliance deviations before they escalate into regulatory breaches or tax problems. Internal controls create checks and balances that prevent errors and identify intentional misconduct.
Essential control mechanisms include:
- Dual authorization for significant transactions and payments
- Monthly reconciliation of commission statements against bank receipts
- Quarterly file reviews assessing advice quality and documentation
- Annual FICA compliance testing on representative samples
- Technology access logs identifying unusual system access patterns
- Client complaint tracking with root cause analysis
These controls need not be elaborate. Even single-person practices can implement segregation of duties through external bookkeeping, peer file reviews with fellow brokers, or compliance consultancy arrangements providing independent oversight.
The Business Case for Excellence in Tax and Compliance
FSPs often perceive tax and compliance obligations as cost centers consuming resources without generating revenue. This perspective misses the substantial business benefits that flow from compliance excellence.
Direct financial benefits include:
- Reduced regulatory penalties and enforcement costs
- Lower professional indemnity insurance premiums reflecting strong risk management
- Tax optimization through structured planning and systematic expense documentation
- Operational efficiency from standardized processes and digital systems
Strategic advantages encompass:
- Enhanced reputation attracting quality clients and product provider partnerships
- Business value appreciation when considering succession planning or sale
- Competitive differentiation in markets where compliance failures attract media attention
- Representative attraction and retention through professional practice environments
The World Bank’s global tax programme research demonstrates that businesses investing in compliance infrastructure achieve superior long-term financial performance compared to those treating compliance as mere obligation.
Clients increasingly evaluate FSP selection based on compliance credentials, recognizing that proper governance protects their interests. Your ability to demonstrate systematic tax and compliance management becomes a marketing differentiator rather than background requirement.
Emerging Trends Affecting Tax and Compliance in 2026
Financial services regulation continues evolving, with several developments likely to affect independent brokers and FSPs during 2026 and beyond.
Digital Reporting and Real-Time Compliance
SARS and the FSCA are progressively implementing digital reporting platforms enabling real-time data submission and automated compliance verification. The shift from periodic manual submissions toward continuous digital reporting will accelerate during 2026.
FSPs should prepare by:
- Ensuring technology systems can generate machine-readable compliance reports
- Implementing digital signature and authentication capabilities
- Establishing secure API connections where platforms offer automated submission
- Building internal capacity to interpret automated compliance feedback
Early adopters of digital reporting typically experience smoother implementation compared to those waiting until mandatory compliance dates.
Enhanced Enforcement and Penalties
Both tax and regulatory authorities demonstrate increasing willingness to impose substantial penalties for non-compliance. The FSCA has published numerous enforcement actions during 2025 and early 2026, signaling that regulatory forbearance has ended.
Penalty amounts now frequently exceed historical norms, with the FSCA imposing fines reaching millions of rand for serious FAIS violations. SARS similarly applies understatement penalties, interest charges, and criminal prosecution for egregious tax non-compliance.
This enforcement intensity makes prevention exponentially more cost-effective than remediation. FSPs who previously accepted occasional compliance lapses as business cost must fundamentally recalibrate risk tolerance.
Increased Focus on Consumer Outcomes
Regulatory philosophy is shifting from input-based compliance (following prescribed processes) toward outcome-based assessment (achieving fair customer treatment). This shift affects how FSPs demonstrate tax and compliance adequacy.
Practical implications include:
- Documentation emphasizing client benefit analysis rather than procedural completion
- Product recommendations justified through suitability assessment rather than commission neutrality claims
- Complaints data analyzed for systemic issues rather than resolved individually
- Fee and commission structures demonstrating value proposition to clients
FSPs who adapt to outcome-focused regulation position themselves favorably as regulatory frameworks continue evolving toward principles-based rather than rules-based approaches.
Navigating tax and compliance obligations successfully requires independent financial brokers and FSPs to adopt systematic frameworks that address POPIA, FICA, FAIS, and COFI requirements whilst optimizing tax positions. The intersection of these regulatory dimensions creates complexity, yet also offers opportunities for competitive differentiation through compliance excellence.
For independent brokers and FSP compliance officers seeking implementation support:
Holistic Compliance Management Solutions offers specialized guidance tailored to South African financial services providers. Whether you need FICA RMCP development, regulatory examination preparation, or comprehensive compliance monitoring, our team provides practical solutions aligned with broker workflows.
Schedule FICA training that includes:
- Risk Management and Compliance Programme drafting customized to your practice
- Client onboarding procedures with documentation templates
- Ongoing monitoring protocols and annual review frameworks
- Representative training materials and competency assessment tools
This training is designed for independent brokers, FSP compliance officers, and financial advisor practices requiring structured FICA implementation support. Contact Holistic Compliance Management Solutions (Pty) Ltd to build a compliance framework that protects your business whilst supporting sustainable growth.